Quick answer: Homeowners insurance may pay to repair or replace a roof damaged by a sudden event your policy covers, such as a windstorm or a tree that comes down in a storm. A roof that is simply old and worn out is typically not a covered loss, and in every case your policy and your insurance company decide.
This article is general information, not insurance or legal advice. Read your policy and call your agent or insurer about your own coverage.
When does homeowners insurance pay for a roof?
Insurance pays when a covered loss damages the roof. The Washington Office of the Insurance Commissioner (OIC) explains in its consumer guide to homeowner insurance that dwelling coverage provides for the repair or replacement of the damaged portion of your home due to a covered loss.
What counts as covered depends on the type of policy. The National Association of Insurance Commissioners (NAIC) says in its homeowners insurance shopping tool that the most common policy form covers your home against all perils except those listed as exclusions in the policy. More basic forms cover only the causes they name, and the NAIC's list of those includes wind and hail.
Does insurance cover a roof that is just old?
Typically no. Insurance is built around a covered loss, meaning something that happened, and a roof reaching the end of its life is wear, not an event.
The NAIC shopping tool tells homeowners to ask whether a policy covers "damage from deterioration, such as foundation settling, wear and tear." If your roof is worn out and nothing sudden damaged it, plan to pay for the replacement yourself. Our Seattle roof cost guide shows what to expect.
What is the difference between replacement cost and actual cash value?
It is the difference between a full payment and a payment reduced for the age of your roof. The OIC's home insurance page defines the two this way:
| Coverage type | What it pays |
|---|---|
| Replacement cost | Pays to repair or replace your property at today's cost without deducting for depreciation |
| Actual cash value | Pays the amount to replace or repair your property, minus how much it has depreciated |
The OIC says replacement cost coverage is standard on most homeowner policies. The roof can be an exception. The NAIC's Post-Disaster Claims Guide warns that even on a replacement cost policy, the policy may pay actual cash value on your roof and replacement cost on the rest of the home. It also notes that some policies have a special deductible that applies to the roof.
Check your declarations page, then ask your agent one direct question: "How does this policy pay on my roof?"
Will insurance pay for a better roof than I had?
Generally no. The NAIC guide says replacement cost policies cover repairs or replacement with property of like kind and quality, and that a policy is not intended to pay for upgrades. Its own example is a roof: a policy would cover another 3-tab shingle roof, not a more expensive slate roof.
What should I do right after storm damage to my roof?
Stop more damage first, then call your agent. The OIC's guide and its page on steps to take after home damage or a loss give this advice:
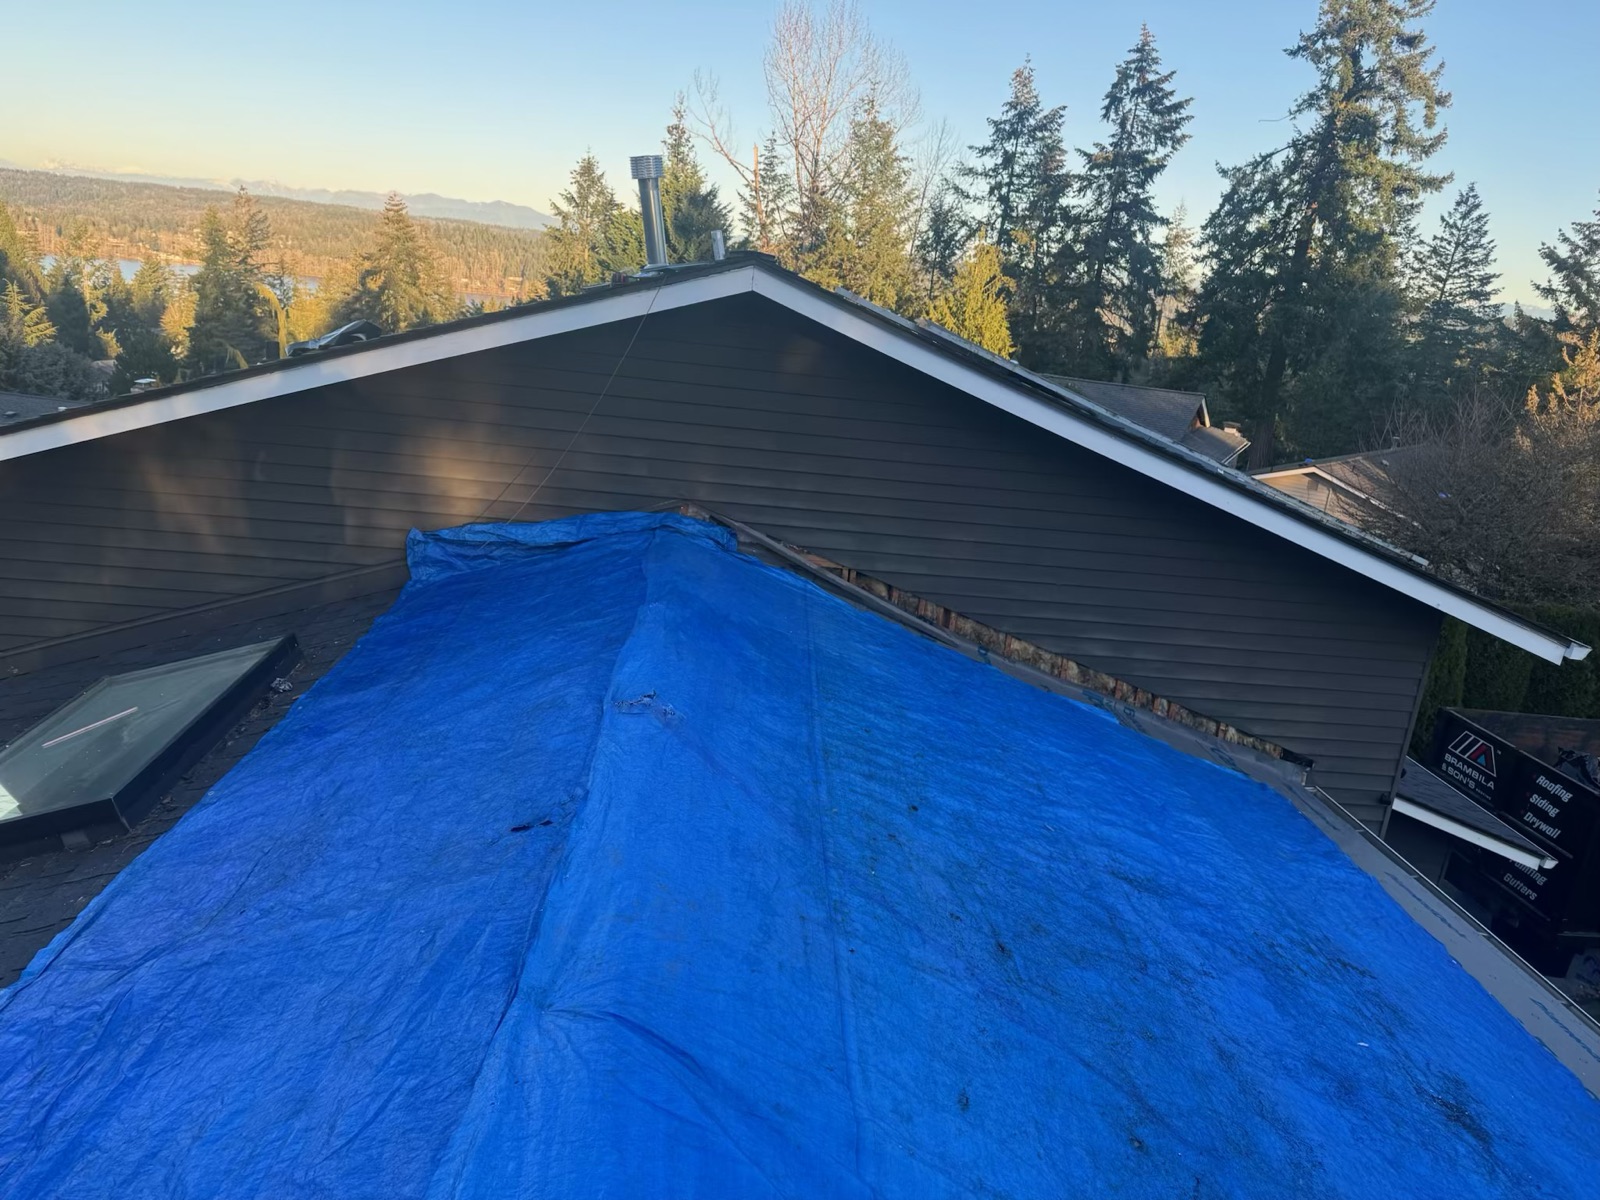
- Protect the property from further damage. Temporary repairs such as a tarp are fine. Save the receipts.
- Do not make permanent repairs yet. The OIC says to wait until after your insurance company has inspected the damaged property.
- Ask if you are covered. The OIC suggests asking your agent or company whether the loss is covered before you file a claim.
- Document the loss. Be ready to provide receipts, photos, or other documentation, and keep copies of everything.
More on how we handle this is on our storm damage and insurance page.
What are my rights on a roof claim in Washington?
You have several, according to the OIC's page on steps after a loss:
- The insurance company should inspect the damage within 30 days from the date you filed your claim.
- Within 30 days, the insurer should accept or deny the claim, or tell you in writing why it needs more time.
- You have the right to select your own contractor. The insurer may recommend one, but the choice is yours.
- Your insurer cannot depreciate labor costs when it determines the actual cash value of a property claim. The OIC says this is not allowed in Washington state.
- If a contractor asks you to sign an assignment of benefits, talk to your agent or company first. The OIC warns it could let the contractor settle the claim without your approval.
If you get stuck, the OIC's consumer hotline is 800-562-6900, and you can file a complaint at insurance.wa.gov.
How can a roofer help with an insurance claim?
A roofer's job is to show what happened to the roof and what it takes to fix it. BSR Constructions LLC documents storm damage and works with the insurance carrier on covered claims.
What a roofer cannot do is promise that a claim will be approved. No contractor can. The policy and the insurer decide.
If you think a storm damaged your roof, request a free inspection and estimate or call (206) 656-4999. Paying yourself? Our free roof cost calculator will show you a price in about 20 seconds.
BSR Constructions LLC is a family-owned, licensed and insured Seattle roofing contractor rated 4.9 stars on Google. This article is general information, not insurance or legal advice. Your policy and your insurer decide what is covered. Call (206) 656-4999 with questions about your roof.